
Can lenders see soft inquiries?
Summary of the article:
Can other lenders see soft inquiries?
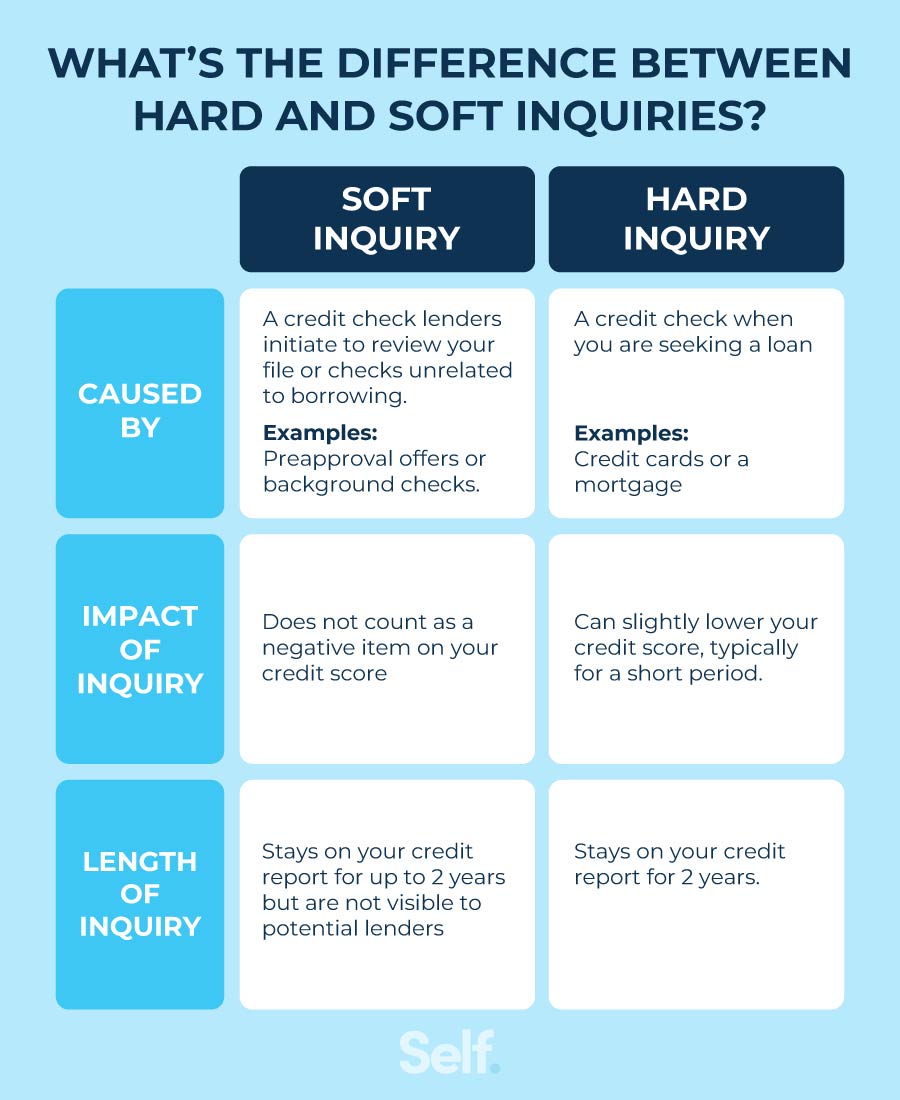
Soft inquiries or soft credit pulls do not impact credit scores and don't look bad to lenders. In fact, lenders can't see soft inquiries at all because they will only show up on the credit reports you check yourself (aka consumer disclosures).
Frequently Asked Questions:
1. Can lenders see soft credit checks?
A soft credit check doesn't leave a visible footprint on your credit file, but it is recorded. This means no other lenders can see it. A soft credit check won't impact your credit score, but, you'll be able to see if anyone has checked your credit history.
2. Do soft inquiries affect mortgage loans?
Unlike a hard pull, a soft pull won't impact your credit score. Your mortgage lender wants to make sure that both credit reports match, and if they don't, you may need to provide additional documentation or send your loan application through underwriting a second time.
3. Who can see soft credit inquiries?
Since soft inquiries aren't connected to a specific application for new credit, they're only visible to you when you view your credit reports.
4. What do lenders see in a soft pull?
A soft pull credit check shows the same information that you can find on a hard pull. It will show a customer's lines of credit and loans. It will outline their payment history. It will also show any accounts that have been sent to a collection agency or if they have a tax lien.
5. What do lenders see when they do a soft pull?
A soft credit check shows the same information as a hard inquiry. This includes your loans and lines of credit as well as their payment history and any collections accounts, tax liens, or other public records in your name.
6. What can a lender see on a soft credit pull?
A soft pull credit check shows the same information that you can find on a hard pull. It will show a customer's lines of credit and loans. It will outline their payment history. It will also show any accounts that have been sent to a collection agency or if they have a tax lien.
7. How many soft inquiries are too many?
Soft inquiries don't drop your credit score, so there isn't a number that could be considered too much.
8. What 4 things do lenders look at?
Lenders look at your income, employment history, savings and monthly debt payments, and other financial obligations to make sure you have the means to comfortably take on a mortgage.
9. How long do soft pulls stay on a credit report?
Soft inquiries will only stay on your credit reports for 12-24 months. And remember: Soft inquiries won't affect your credit scores. Lenders may be concerned if you have too many hard inquiries on your credit report within a short period of time. However, there are some exceptions to this.
10. How many points is a soft credit pull?
A soft inquiry does not affect your credit score in any way. When a lender performs a soft inquiry on your credit file, the inquiry might appear on your credit report, but it won't impact your credit score.
[/wpremark]
Can other lenders see soft inquiries
Soft inquiries or soft credit pulls
These do not impact credit scores and don't look bad to lenders. In fact, lenders can't see soft inquiries at all because they will only show up on the credit reports you check yourself (aka consumer disclosures).
Cached
Can lenders see soft credit checks
A soft credit check doesn't leave a visible footprint on your credit file, but it is recorded. This means no other lenders can see it. A soft credit check won't impact your credit score, but, you'll be able to see if anyone has checked your credit history.
Do soft inquiries affect mortgage loans
Unlike a hard pull, a soft pull won't impact your credit score. Your mortgage lender wants to make sure that both credit reports match, and if they don't, you may need to provide additional documentation or send your loan application through underwriting a second time.
Cached
Who can see soft credit inquiries
Since soft inquiries aren't connected to a specific application for new credit, they're only visible to you when you view your credit reports.
Cached
What do lenders see in a soft pull
A soft pull credit check shows the same information that you can find on a hard pull. It will show a customer's lines of credit and loans. It will outline their payment history. It will also show any accounts that have been sent to a collection agency or if they have a tax lien.
What do lenders see when they do a soft pull
A soft credit check shows the same information as a hard inquiry. This includes your loans and lines of credit as well as their payment history and any collections accounts, tax liens or other public records in your name.
What can a lender see on a soft credit pull
A soft pull credit check shows the same information that you can find on a hard pull. It will show a customer's lines of credit and loans. It will outline their payment history. It will also show any accounts that have been sent to a collection agency or if they have a tax lien.
How many soft inquiries is too many
Soft inquiries don't drop your credit score, so there isn't a number that could be considered too much.
What 4 things do lenders look at
Lenders look at your income, employment history, savings and monthly debt payments, and other financial obligations to make sure you have the means to comfortably take on a mortgage.
How long do soft pulls stay on credit report
12-24 months
Soft inquiries will only stay on your credit reports for 12-24 months. And remember: Soft inquiries won't affect your credit scores. Lenders may be concerned if you have too many hard inquiries on your credit report within a short period of time. However, there are some exceptions to this.
How many points is a soft credit pull
A soft inquiry does not affect your credit score in any way. When a lender performs a soft inquiry on your credit file, the inquiry might appear on your credit report but it won't impact your credit score.
Is having 10 inquiries bad
However, multiple hard inquiries can deplete your score by as much as 10 points each time they happen. People with six or more recent hard inquiries are eight times as likely to file for bankruptcy than those with none. That's way more inquiries than most of us need to find a good deal on a car loan or credit card.
Is it bad to have 5 inquiries
There's no such thing as “too many” hard credit inquiries, but multiple applications for new credit accounts within a short time frame could point to a risky borrower. Rate shopping for a particular loan, however, may be treated as a single inquiry and have minimal impact on your creditworthiness.
What are the 3 C’s of credit that lenders look for in a loan applicant
Students classify those characteristics based on the three C's of credit (capacity, character, and collateral), assess the riskiness of lending to that individual based on these characteristics, and then decide whether or not to approve or deny the loan request.
What are the 5 C’s of lenders
The five Cs of credit are important because lenders use these factors to determine whether to approve you for a financial product. Lenders also use these five Cs—character, capacity, capital, collateral, and conditions—to set your loan rates and loan terms.
Do lenders care about soft pulls
When the soft pull comes back, lenders have a better understanding of a customer's creditworthiness. This allows them to determine how well the consumer is managing their credit and their potential risk. From there, lenders can pre-approve them for a mortgage or line of credit.
Can other creditors see soft pulls
Soft inquiries are also not disputable. However, remember that potential lenders won't be able to see them (except for insurance companies and debt-settlement companies as we've noted earlier).
Is 4 hard inquiries too many
There's no such thing as “too many” hard credit inquiries, but multiple applications for new credit accounts within a short time frame could point to a risky borrower. Rate shopping for a particular loan, however, may be treated as a single inquiry and have minimal impact on your creditworthiness.
How to get 800 credit score in 45 days
Here are 10 ways to increase your credit score by 100 points – most often this can be done within 45 days.Check your credit report.Pay your bills on time.Pay off any collections.Get caught up on past-due bills.Keep balances low on your credit cards.Pay off debt rather than continually transferring it.
What type of credit do lenders look at
FICO credit score
Which credit score do lenders actually use Most lenders use the FICO credit score when assessing your creditworthiness for a loan. According to FICO, 90% of the top lenders use FICO credit scores.
What are the 5 Cs of underwriting
One of the first things all lenders learn and use to make loan decisions are the “Five C's of Credit": Character, Conditions, Capital, Capacity, and Collateral. These are the criteria your prospective lender uses to determine whether to make you a loan (and on what terms).
What are the 3 R’s of credit
3 R's of credit: Returns, Repayment Capacity and Risk bearing ability.
What are the 5 P’s of credit
Since the birth of formal banking, banks have relied on the “five p's” – people, physical cash, premises, processes and paper.
How long does it take to go from 550 to 750 credit score
How Long Does It Take to Fix Credit The good news is that when your score is low, each positive change you make is likely to have a significant impact. For instance, going from a poor credit score of around 500 to a fair credit score (in the 580-669 range) takes around 12 to 18 months of responsible credit use.
How long does it take to go from 650 to 800 credit score
Depending on where you're starting from, It can take several years or more to build an 800 credit score. You need to have a few years of only positive payment history and a good mix of credit accounts showing you have experience managing different types of credit cards and loans.


0 Comments