
How do I get preapproved for a FHA loan?
Summary of the Article: Can You Get Preapproved for an FHA Loan?
Getting preapproved for an FHA loan is possible if you meet the minimum credit score, debt-to-income ratio, and other necessary eligibility requirements. This can help you get great FHA loan rates and be on your way to home ownership.
15 Questions About Getting Preapproved for an FHA Loan
- How long does it take to get preapproved for an FHA loan?
The FHA pre-approval process can be completed in as little as one day if you provide all the required documentation quickly. - What is the first step to getting an FHA loan?
The first step is to perform a self-assessment to determine if FHA mortgage insurance is right for you. Then, choose a lender from the list of lenders active in the program and undergo a preliminary review. - What credit score do you need for an FHA loan?
To qualify for an FHA loan, a credit score of 580 or higher is required. If you can make a 10% down payment, a credit score in the range of 500-579 may be accepted. - What will disqualify you from an FHA loan?
A high debt-to-income ratio, poor credit, or insufficient funds to cover the required down payment, monthly mortgage payments, or closing costs can disqualify you from getting an FHA loan. - Why would a house not accept an FHA loan?
Some sellers may not accept FHA loans due to their stricter approval and appraisal requirements. Additionally, the more lenient financial requirements of FHA loans may create a negative perception for sellers. - Which borrower who wants an FHA loan would apply directly to?
Borrowers who want an FHA loan can apply directly with the bank or lender of their choice. Most banks and mortgage lenders are approved for FHA loans, and borrowers can also apply for pre-approval. - Can an FHA loan be denied after pre-approval?
Pre-approval for an FHA loan does not guarantee final approval, but there are steps you can take if your loan is denied. Understanding the reasons for denial can help clarify issues, improve your financial situation, or seek another lender. - Is it harder to qualify for an FHA loan?
In general, it is easier to qualify for an FHA loan compared to a conventional loan. FHA loans allow for lower credit scores and have more lenient requirements. - What is the fastest time to close on an FHA loan?
On average, it takes around 47 days to close on an FHA mortgage loan. FHA refinances are faster, with an average closing time of 32 days. - Is it hard to get an FHA loan?
To qualify for an FHA loan, you need a 3.5% down payment, a credit score of 580 or higher, and a debt-to-income ratio of 43% or lower.
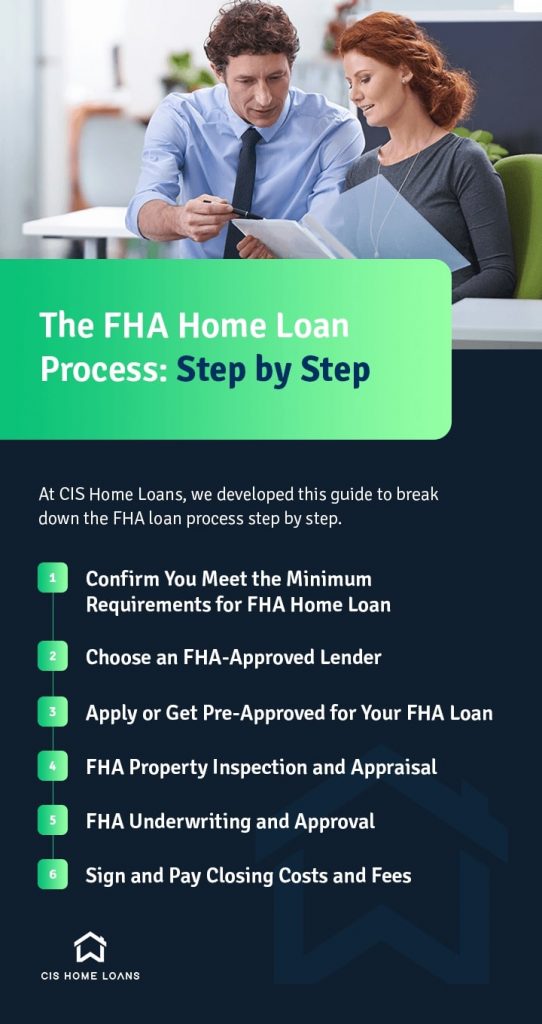
Can you get pre approved for FHA
As long as you meet the minimum credit score, debt-to-income ratio, and other necessary eligibility requirements, you could be FHA pre-approved and pre-qualified with great FHA loan rates and on your way to home ownership.
Cached
How long does it take to get pre approved for an FHA loan
one day
How Long Does it Take to get Pre Approved for an FHA Loan The FHA pre-approval can be done in one day if you provide the lender with the documentation that he or she needs quickly. Providing only some of the documentation that the lender needs will only delay your pre-approval.
Cached
What is the first step to getting an FHA loan
Self-Assessment. The first step is to perform a self-assessment to determine if FHA mortgage insurance is right for you.Choose a Lender. If you do not already have a mortgage lender, FHA maintains a List of Lenders who are active in the hospital mortgage insurance program.Preliminary Review.
What credit score do you need for an FHA
580 and higher
An FHA loan requires a minimum 3.5% down payment for credit scores of 580 and higher. If you can make a 10% down payment, your credit score can be in the 500 – 579 range. Rocket Mortgage® requires a minimum credit score of 580 for FHA loans.
What will disqualify you from an FHA loan
The three primary factors that can disqualify you from getting an FHA loan are a high debt-to-income ratio, poor credit, or lack of funds to cover the required down payment, monthly mortgage payments or closing costs.
Why would a house not accept an FHA loan
Why Do Some Sellers Not Accept FHA Loans Some home sellers see the FHA loan as a riskier loan than a conventional loan because of its stricter approval and appraisal requirements. Additionally, the loan's more lenient financial requirements for borrowers may leave the seller with a negative perception.
Which borrower who wants an FHA loan would apply directly to
You apply for an FHA loan directly with the bank or other lender that you choose. Most banks and mortgage lenders are approved for FHA loans. You can apply for pre-approval of an FHA loan with the lender you choose.
Can an FHA loan be denied after pre-approval
Being pre-approved for an FHA loan doesn't guarantee your mortgage loan will reach conditional approval or final approval, but there are steps you can take if it's denied. Once you understand why your loan was denied, you can ask to clarify issues, improve your financial portrait, or work with another lender.
Is it harder to qualify for an FHA loan
In general, it's easier to qualify for an FHA loan than for a conventional loan, which is a mortgage that isn't insured or guaranteed by the federal government. Here are some key differences between FHA and conventional loans: Credit score and history: FHA loans allow for lower credit scores than conventional loans.
What is the fastest time to close on a FHA loan
It takes around 47 days to close on an FHA mortgage loan. FHA refinances are faster and take around 32 days to close on average.
Is it hard to get a FHA loan
To qualify for an FHA loan, you need a 3.5% down payment, 580 credit score, and 43% DTI ratio. An FHA loan is easier to get than a conventional mortgage. The FHA offers several types of home loans, including loans for home improvements.
How often do FHA loans get denied
How often are FHA loans denied in underwriting According to a 2020 report by the Consumer Financial Protection Bureau (CFPB), FHA borrowers are more likely to be denied for FHA loans than all other loan types: 14.1% of FHA purchase loans and 22.2% of FHA refinance applications were turned down in 2020.
Who gets denied an FHA loan
There are three popular reasons – bad credit, high debt-to-income ratio, and overall insufficient money to cover the down payment and closing costs of a home.
What is one disadvantage of an FHA loan
Here are some FHA home loan disadvantages: An extra cost – an upfront mortgage insurance premium (MIP) of 2.25% of the loan's value. The MIP must either be paid in cash when you get the loan or rolled into the life of the loan. Home price qualifying maximums are set by FHA.
Why do people not accept FHA loans
Unfortunately, sellers often perceive the FHA loan approval process as risky because of the FHA's relatively lenient financial requirements and stricter appraisal and property standards.
Why do sellers reject FHA loans
FHA Underwriting Worries Some Sellers
Because FHA loans help low- to moderate-income borrowers with less-than-stellar credit become homeowners, sellers may feel that FHA buyers are less likely to be approved for a loan than conventional borrowers.
What is the 3 7 3 rule in mortgage
Timing Requirements – The “3/7/3 Rule”
The initial Truth in Lending Statement must be delivered to the consumer within 3 business days of the receipt of the loan application by the lender. The TILA statement is presumed to be delivered to the consumer 3 business days after it is mailed.
How often do underwriters deny FHA loans
about 1 in 10 mortgage
How often does an underwriter deny a loan A mortgage underwriter typically denies about 1 in 10 mortgage loan applications. A mortgage loan application can be denied for many reasons, including a borrower's low credit score, recent employment change or high debt-to-income ratio.
What disqualifies you from an FHA loan
The three primary factors that can disqualify you from getting an FHA loan are a high debt-to-income ratio, poor credit, or lack of funds to cover the required down payment, monthly mortgage payments or closing costs.
Why would an FHA loan not be accepted
Why Do Some Sellers Not Accept FHA Loans Some home sellers see the FHA loan as a riskier loan than a conventional loan because of its stricter approval and appraisal requirements. Additionally, the loan's more lenient financial requirements for borrowers may leave the seller with a negative perception.
Why do sellers avoid FHA
FHA Underwriting Worries Some Sellers
Because FHA loans help low- to moderate-income borrowers with less-than-stellar credit become homeowners, sellers may feel that FHA buyers are less likely to be approved for a loan than conventional borrowers.
What is the golden rule on a mortgage
The 28/36 rule states that your total housing costs should not exceed 28% of your gross monthly income and your total debt payments should not exceed 36%. Following this rule aims to keep borrowers from overextending themselves for housing and other costs.
What is the 80% mortgage rule
The first mortgage covers 80% of the price of your home, the second mortgage covers 10% and the remaining 10% is your down payment. An 80-10-10 mortgage is designed to help you avoid private mortgage insurance and sidestep the standard 20% down payment. However, it comes with a few drawbacks.
What would disqualify you from an FHA loan
The three primary factors that can disqualify you from getting an FHA loan are a high debt-to-income ratio, poor credit, or lack of funds to cover the required down payment, monthly mortgage payments or closing costs.
Why are FHA closing costs so high
Because FHA closing costs include the upfront MIP, an FHA loan can have average closing costs on the higher end of the typical 3% – 6% range. That doesn't diminish in any way the value of getting an FHA mortgage, with its low down payment, lower interest rates and flexible underwriting.


0 Comments