
What is an HO 1 policy?
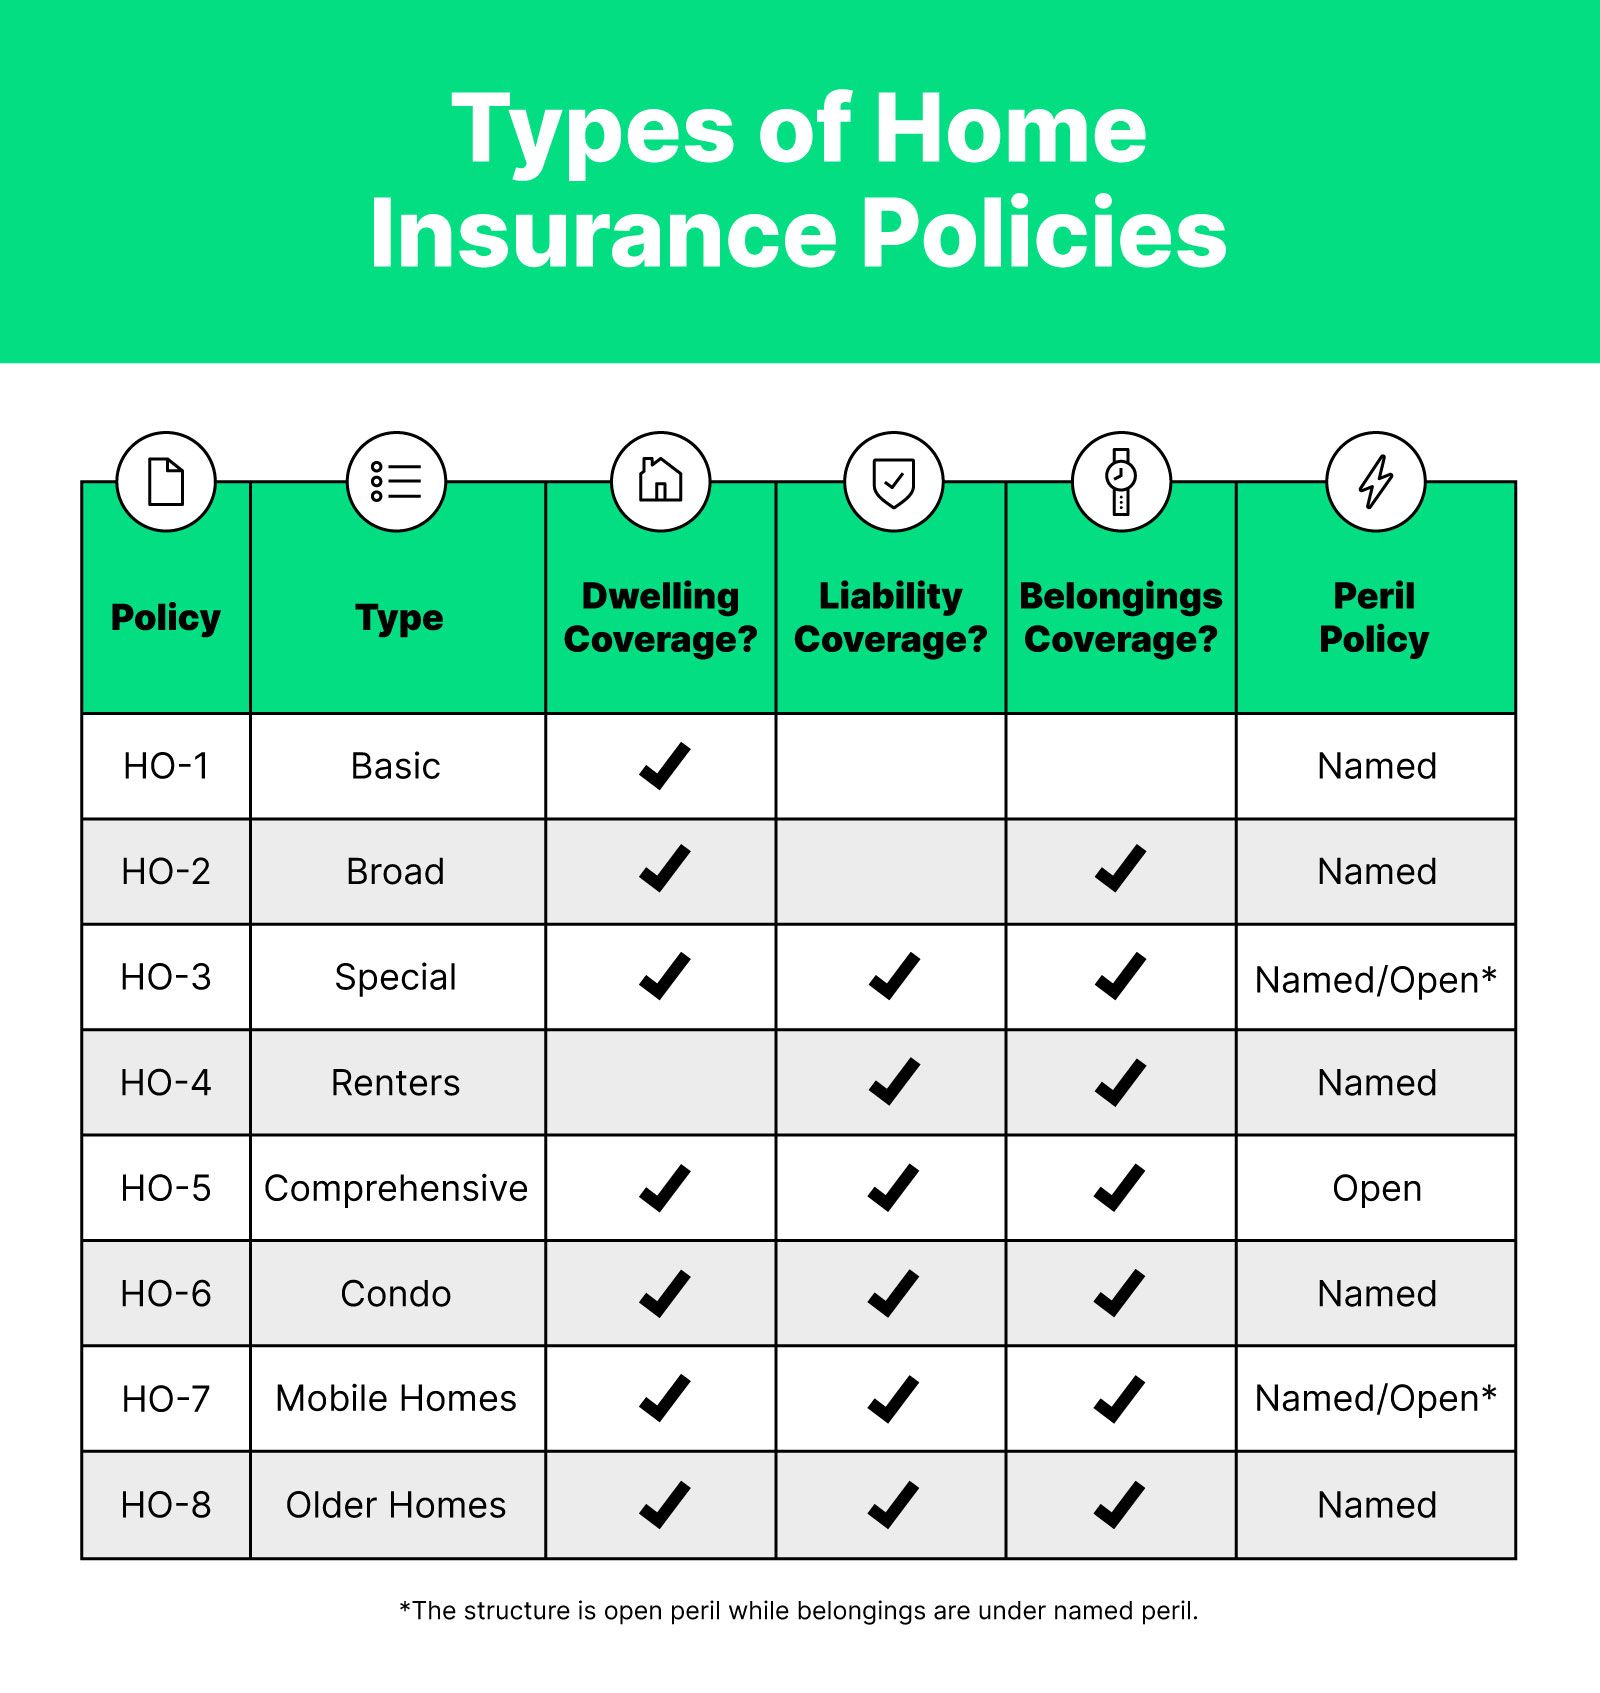
Summary of Home Insurance Policies
What is an HO-1 policy?
An HO-1 policy, known as a “bare bones” plan, offers the most basic form of home insurance for property owners. It’s a named peril policy, typically providing coverage for Other Structures, Personal Property, Loss of Use, Liability, and the 10 common perils listed, including damage from theft, fire, and hail.
What is the difference between HO1 and HO3 insurance?
HO1 and HO2 policies are examples of “named perils policies.” That means they only cover dangers that are specifically listed in the policy. HO3 policies are “open peril policies.” That means they’ll cover all dangers except those specifically excluded in the policy documents.
What is the difference between an HO1 and an HO-2 policy?
HO-2 policies protect against everything covered by the HO-1, plus two extra perils: damage from falling objects and water damage from accidental overflow of plumbing, heating, ventilation, and air conditioning (HVAC), and household appliances.
What is an HO-2 homeowners policy?
An HO-2 policy is a type of homeowners insurance that only covers damages caused by perils specifically named in your policy. An HO-2 typically covers 16 named perils, including damage from fire and lightning, windstorms and hail, and theft.
Which of the following is not covered in the standard HO-1 policy?
Many things that aren’t covered under your standard policy typically result from neglect and a failure to properly maintain the property. Termites and insect damage, bird or rodent damage, rust, rot, mold, and general wear and tear are not covered.
What is the difference between an HO-2 policy and an HO3?
In an HO2 policy, only perils listed in the policy are covered. In an HO3 policy, all perils are covered except for the exclusions listed in the policy. An HO2 is often called a “broad form policy,” whereas an HO3 is often called a “special form policy.”
What does HO3 insurance cover?
HO-3 homeowners insurance covers you for a variety of other expenses related to your home beyond your physical property. Common coverages include personal liability, loss of use, and medical payments. The most important of these remaining features is personal liability coverage.
What is HO3 policy for?
A homeowners insurance (HO-3) policy is a coverage plan that covers your home’s structure, your personal belongings, and liability in the event of damage or injury. Typically, an HO-3 policy will also cover additional living expenses and protection for other structures on your property.
What does HO-3 mean on homeowners insurance?
HO-3 policies cover liability expenses and costs of living elsewhere. HO-3 homeowners insurance covers you for a variety of other expenses related to your home beyond your physical property. Common coverages include personal liability, loss of use, and medical payments.
What is an HO-3 homeowners insurance policy?
A homeowners insurance (HO-3) policy is a coverage plan that covers your home’s structure, your personal belongings, and liability in the event of damage or injury. Typically, an HO-3 policy will also cover additional living expenses and protection for other structures on your property.
What is an HO3 policy?
An HO-3 insurance policy is a type of homeowners insurance that provides coverage for your home’s structure, your personal belongings, and liability in the event of damage or injury. It offers more comprehensive coverage compared to HO-1 and HO-2 policies.
What is a h0 1 policy
An HO-1 policy, known as a “bare bones” plan, offers the most basic form of home insurance for property owners. It's a named peril policy, typically providing coverage for Other Structures, Personal Property, Loss of Use, Liability and the 10 common perils listed, including damage from theft, fire, and hail.
Cached
What is the difference between HO1 and HO3 insurance
HO1 and HO2 policies are examples of “named perils policies.” That means they only cover dangers that are specifically listed in the policy. HO3 policies are “open peril policies”. That means they'll cover all dangers except those specifically excluded in the policy documents.
Cached
What is the difference between an HO 1 and an HO-2 policy
HO-2 policies protect against everything covered by the HO-1, plus two extra perils: damage from falling objects and water damage from accidental overflow of plumbing; heating, ventilation and air conditioning (HVAC); and household appliances.
What is an HO-2 homeowners policy
An HO-2 policy is a type of homeowners insurance that only covers damages caused by perils specifically named in your policy. An HO-2 typically covers 16 named perils, including damage from fire and lightning, windstorms and hail, and theft.
Which of the following is not covered in the standard HO 1 policy
Many things that aren't covered under your standard policy typically result from neglect and a failure to properly maintain the property. Termites and insect damage, bird or rodent damage, rust, rot, mold, and general wear and tear are not covered.
What is the difference between an HO 2 policy and an HO3
In an HO2 policy, only perils listed in the policy are covered. In an HO3 policy, all perils are covered except for the exclusions listed in the policy. An HO2 is often called a “broad form policy,” whereas an HO3 is often called a “special form policy.”
What does HO3 insurance cover
HO-3 homeowners insurance covers you for a variety of other expenses related to your home beyond your physical property. Common coverages include personal liability, loss of use and medical payments. The most important of these remaining features is personal liability coverage.
What is HO3 policy for
A homeowners insurance (HO-3) policy is a coverage plan that covers your home's structure, your personal belongings and liability in the event of damage or injury. Typically, an HO-3 policy will also cover additional living expenses and protection for other structures on your property.
What does HO-3 mean on homeowners insurance
HO-3 policies cover liability expenses and costs of living elsewhere. HO-3 homeowners insurance covers you for a variety of other expenses related to your home beyond your physical property. Common coverages include personal liability, loss of use and medical payments.
What is an HO-3 homeowners insurance policy
A homeowners insurance (HO-3) policy is a coverage plan that covers your home's structure, your personal belongings and liability in the event of damage or injury. Typically, an HO-3 policy will also cover additional living expenses and protection for other structures on your property.
What is an HO 3 policy
An HO-3 insurance policy is a form of home insurance that protects policyholders against property damage, legal liabilities and other expenses associated with unexpected disasters befalling your home.
What is under an HO 3 policy
A homeowners insurance (HO-3) policy is a coverage plan that covers your home's structure, your personal belongings and liability in the event of damage or injury. Typically, an HO-3 policy will also cover additional living expenses and protection for other structures on your property.
What are 2 things not covered in homeowners insurance
Termites and insect damage, bird or rodent damage, rust, rot, mold, and general wear and tear are not covered. Damage caused by smog or smoke from industrial or agricultural operations is also not covered. If something is poorly made or has a hidden defect, this is generally excluded and won't be covered.
What are four things not covered by homeowners insurance
Standard homeowners insurance policies typically do not include coverage for valuable jewelry, artwork, other collectibles, identity theft protection, or damage caused by an earthquake or a flood.
What is an HO-3 homeowners policy
HO-3 insurance includes all of the standard home insurance coverage types, including dwelling, personal property, other structures, liability, medical payments and additional living expenses coverage.
What is excluded from HO3 policy
Typically, the following are excluded on an open peril policy: Freezing pipes and systems in vacant dwellings. Damage to foundations or pavements from ice and water weight. Theft from a dwelling under construction.
Which is better HO3 or HO5
The HO3 and HO5 policies both cover a policyholder's house on an open peril basis. The difference is in how it protects personal property. HO5 comes with better coverage, meaning it also comes with a higher price. The value is based on whether the additional cost is worth the benefit.
What is the HO 4 policy
HO-4 insurance is the technical term for renters insurance. While your landlord insures the physical structure of the building you live in, an HO-4 policy protects your personal possessions if they are damaged under certain circumstances. On top of that, most HO-4 policies typically provide liability insurance.
What is HO 5 homeowners insurance policy
What is an HO5 policy Sometimes called the comprehensive form, an HO5 policy is a type of home insurance written on an open-perils basis. This means your insurer covers damage to your home and personal property when it's caused by an event, or peril, as long as it's not listed as an exclusion in the policy.
What is the HO-4 policy
HO-4 insurance is the technical term for renters insurance. While your landlord insures the physical structure of the building you live in, an HO-4 policy protects your personal possessions if they are damaged under certain circumstances. On top of that, most HO-4 policies typically provide liability insurance.
What is an HO 7 policy
The HO-7 policy is an insurance policy for mobile home owners. It covers the dwelling and other structures, personal property, personal liability, loss of use, and medical expenses of others for mobile homes, RVs, sectional homes, modular homes, and trailers while stationary.
What is an HO 5 policy
An HO-5 policy is a homeowners insurance policy type that covers your home and personal belongings under open perils coverage, except for certain exclusions. This differs slightly from a standard HO-3 homeowners policy, which covers your home as open perils but your personal possessions only for named perils.
What is the most common damage to your home that insurance does not cover
Earthquake and water damage
In most states, earthquakes, sinkholes, and other earth movements are not covered by your standard policy.
What are some examples of exclusions in an HO property
Common exclusions in even the most comprehensive homeowners policies include: earth movement, such as earthquakes; sinkholes or landslides that damage your home; water damage, such as floods or sewer back-ups that leak through a pipe or seep through the foundation causing damage to your home; damage resulting from …
What is not covered under an HO5
HO5 usually excludes losses caused by: Earth movement. Ordinance or law. Water damage from flood, sewer backup, or water seepage. Power failure.


0 Comments